

A discussion on Quora revealed that there are 4 million entrepreneurs worldwide. In the US alone, there are 11.5 million entrepreneurs and approximately 2.6million venture backed startups. Moreover, the percentage of successful startups is significantly lower than that of unsuccessful ones. With these numbers in mind, we can assume just how important of a role money management plays in a world of “break-even” and “ROI” KPIs.
In order to aid young entrepreneurs and startup founders, here are 6 money management tips that might save the day.
Carefully separate company needs from personal desires. You may want your entire team to have the latest technology access and gadgets, but think twice before creating your paradise. Do you really need it? Can you still perform over 90% with more affordable options? If the answer is Yes, you know what you have to do.
As the infographic below by Mirador Wealth suggests, research before investing especially before going big. The most dangerous enemy is yourself: often, entrepreneurs push themselves into a "make it or break it" world, without realizing you can actually achieve success with baby steps. Empires were not built in a day. Most likely, it took years, decades or even centuries.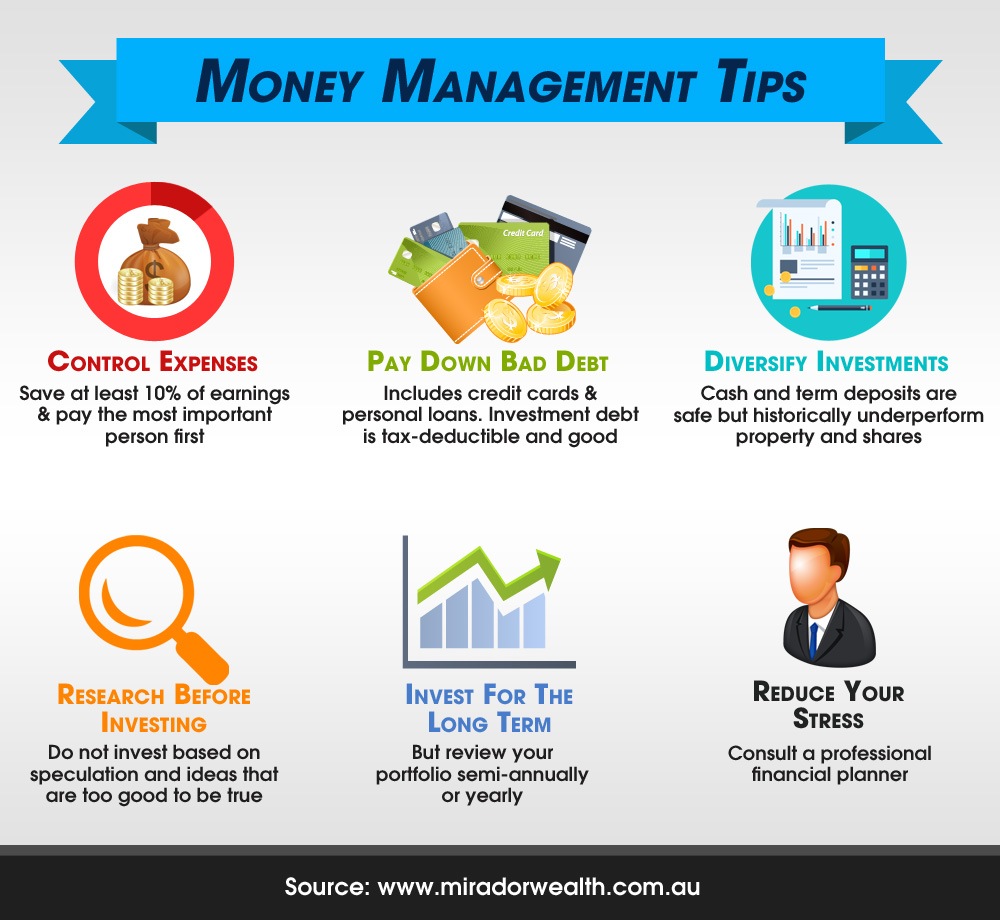 source: Mirador Wealth
In order to aid young entrepreneurs and startup founders, here are 6 money management tips that might save the day.
1. Money Comes With Patience So Don’t Rush It
Before the grand launch, make sure you have a clear business plan and enough funds to cover both your immediate, longterm and unexpected expenses. Your safety net should cover the first three years and by the second year, stop relying 100% on external funding.Carefully separate company needs from personal desires. You may want your entire team to have the latest technology access and gadgets, but think twice before creating your paradise. Do you really need it? Can you still perform over 90% with more affordable options? If the answer is Yes, you know what you have to do.
2. Do What’s Best For Your Business, Not For You
Choose your business partners and employees or contractors with care. Pay attention if you don't want to pay later for the lack of it. Don’t build your startup involving various services just because the people that offer them are your friends. At the end of the day, business is business.As the infographic below by Mirador Wealth suggests, research before investing especially before going big. The most dangerous enemy is yourself: often, entrepreneurs push themselves into a "make it or break it" world, without realizing you can actually achieve success with baby steps. Empires were not built in a day. Most likely, it took years, decades or even centuries.
Personal advice: “Don’t throw the nets into an ocean unless you are absolutely convinced it will bring you more fish.”
3. Don’t Let Competition Distract You
Just because your competitors are “older” on the market and can afford over spending, does not mean you have to follow in their footsteps. You may find that creativity gets you out of tight spots and a small, yet smart strategy can be more fruitful. As seen on Forbes. Be smart and engage your consumers wittily.4. Constantly Keep An Eye On Expenses And Profits
Take into account what your monthly costs are, as well as any changes that can occur. If you don’t have a financial expert, pick up the pen, separate your fixed and variable costs, draw the line and monitor them closely. This alone will help you understand your monthly and quarterly profit, and provide a clear view on growth. The secret recipe is a good accountant + good bookkeeper + open minded business owner.5. Establish Clear Goals
Start with clear goals, as this Inc.com article suggests. Quarterly and yearly goals can do the trick should your startup be a new player on the market. A clear understanding of required resources and realistic deadlines must be taken into account. Important: stay away from these two extreme behaviors:- Setting low goals and thinking you’re exceptional when you’re simply average.
- Setting goals almost impossible to achieve and blaming failure on others.
6. Re-evaluate Throughout the Whole Year
Any small business in its first five years of survival could benefit from this tip. For e.g., should your goal be generating a minimum of USD 5000 profit per month in a collapsing market, then it makes no sense to keep investing. Relax, re-evaluate your position and your odds and adjust your strategy to the “business flow”. Being inflexible might cost much more in the long run.Wrapping It Up
While we all tend to “listen, nod and then do whatever we want”, the best piece of advice that you can follow is to be realistic in terms of investments. Set achievable goals, keep a close eye on the bigger picture and be flexible. Last but not least, as a friend of mine often says: “Be an epic doer!”.
source: Mirador Wealth


